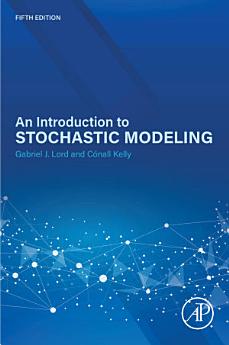
An Introduction to Stochastic Modeling: Edition 5
Sep 2025 · Academic Press
Ebook
600
Pages
family_home
Eligible
info
About this ebook
An Introduction to Stochastic Modeling, Fifth Edition bridges the gap between basic probability and an intermediate level course in stochastic processes, serving as the foundation for either a one-semester or two-semester course in stochastic processes for students familiar with elementary probability theory and calculus. The objectives are to introduce students to the standard concepts and methods of stochastic modeling, to illustrate the rich diversity of applications of stochastic processes in the applied sciences, and to provide an integrated treatment of theory, applications and practical implementation. A well-regarded resource for many years, the text is an ideal foundation for a broad range of students. - Explores realistic applications from a variety of disciplines, including biological, chemical, physical, engineering, and financial examples - Presents a completely new treatment of modeling with stochastic differential equations, and expanded coverage of Brownian motion and martingale processes - New applications of Markov chains to the simulation of chemical reactions via the Gillespie algorithm and to Bayesian inference via the Metropolis-Hastings algorithm - Provides extensive end-of-section exercises sets with answers, as well as numerical illustrations - Each chapter concludes with a section focusing on computational examples, code, and exercises that will empower students to explore concepts in a practical way - Offers online support, sample code and solutions to coding problems for instructors, and electronic access to sample Python code for students
An Introduction to Stochastic Modeling, Fifth Edition bridges the gap between basic probability and an intermediate level course in stochastic processes, serving as the foundation for either a one-semester or two-semester course in stochastic processes for students familiar with elementary probab...
Discover more
About the author
Gabriel J. Lord is Professor of Applied Analysis at Radboud University Nijmegen in the Netherlands since 2019. Prior to this, he was a Professor at the Maxwell Institute in Edinburgh, UK which he joined after a couple of years in industry at the National Physical Laboratory, UK. With over 25 years teaching experience he has been giving lectures on elements of stochastic modeling for the last twenty years. He has co-authored Stochastic Methods in Neuroscience and An Introduction to Computational Stochastic PDEs. His research is in applied and computational mathematics and in particular for stochastic systems and models.Cónall Kelly is Senior Lecturer (Associate Professor) of Financial Mathematics and Chair of the BSc Financial Mathematics and Actuarial Science degree at University College Cork in Ireland. He has taught courses in stochastic analysis and modeling for over 15 years and is the author of the textbook Computation and Simulation for Finance: An Introduction with Python. His research focuses on the qualitative dynamics of stochastic difference and differential equations, the analysis of numerical methods for stochastic systems, and applications in finance and biology.
Gabriel J. Lord is Professor of Applied Analysis at Radboud University Nijmegen in the Netherlands since 2019. Prior to this, he was a Professor at the Maxwell Institute in Edinburgh, UK which he joined after a couple of years in industry at the National Physical Laboratory, UK. With over 25 year...
Rate this ebook
Tell us what you think.
Reading information
Smartphones and tablets
Install the Google Play Books app for Android and iPad/iPhone. It syncs automatically with your account and allows you to read online or offline wherever you are.
Laptops and computers
You can listen to audiobooks purchased on Google Play using your computer's web browser.
eReaders and other devices
To read on e-ink devices like Kobo eReaders, you'll need to download a file and transfer it to your device. Follow the detailed Help Center instructions to transfer the files to supported eReaders.