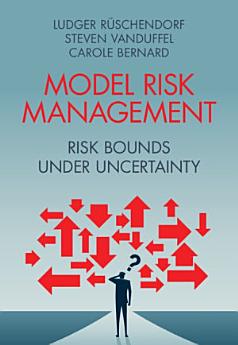
Model Risk Management: Risk Bounds under Uncertainty

· ·
· Cambridge University Press
Ebook
348
Pages

About this ebook

This book provides the first systematic treatment of model risk, outlining the tools needed to quantify model uncertainty, to study its effects, and, in particular, to determine the best upper and lower risk bounds for various risk aggregation functionals of interest. Drawing on both numerical and analytical examples, this is a thorough reference work for actuaries, risk managers, and regulators. Supervisory authorities can use the methods discussed to challenge the models used by banks and insurers, and banks and insurers can use them to prioritize the activities on model development, identifying which ones require more attention than others. In sum, it is essential reading for all those working in portfolio theory and the theory of financial and engineering risk, as well as for practitioners in these areas. It can also be used as a textbook for graduate courses on risk bounds and model uncertainty.
This book provides the first systematic treatment of model risk, outlining the tools needed to quantify model uncertainty, to study its effects, and, in particular, to determine the best upper and lower risk bounds for various risk aggregation functionals of interest. Drawing on both numerical an...

Discover more

About the author

Ludger Rüschendorf is Professor of Mathematics at the University of Freiburg. He is author of more than 200 research papers and a number of textbooks, in a variety of subjects in probability, statistics, analysis of algorithms as well as in risk analysis and in mathematical finance. A main topic in his research is the modeling and analysis of dependence structures.

Steven Vanduffel is Professor in Risk Management at the Solvay Business School at Vrije Universiteit Brussel. He has authored papers for leading journals including 'Journal of Risk and Insurance,' 'Finance and Stochastics,' 'Mathematical Finance,' and 'Journal of Econometrics.' He has won prizes including the Robert I. Mehr Award (2022), the Robert C. Witt Award (2018), and the Redington Prize (2015).

Carole Bernard is Professor in Finance at Grenoble Ecole de Management and Vrije Universiteit Brussel. She has published articles in leading journals in finance, insurance, operations research, and risk management, including 'Management Science,' 'Journal of Risk and Insurance,' 'Journal of Banking and Finance,' and 'Mathematical Finance.'
Ludger Rüschendorf is Professor of Mathematics at the University of Freiburg. He is author of more than 200 research papers and a number of textbooks, in a variety of subjects in probability, statistics, analysis of algorithms as well as in risk analysis and in mathematical finance. A main topic ...

Rate this ebook

Tell us what you think.

Reading information

Smartphones and tablets
Install the Google Play Books app for Android and iPad/iPhone. It syncs automatically with your account and allows you to read online or offline wherever you are.
Laptops and computers
You can listen to audiobooks purchased on Google Play using your computer's web browser.
eReaders and other devices
To read on e-ink devices like Kobo eReaders, you'll need to download a file and transfer it to your device. Follow the detailed Help Center instructions to transfer the files to supported eReaders.